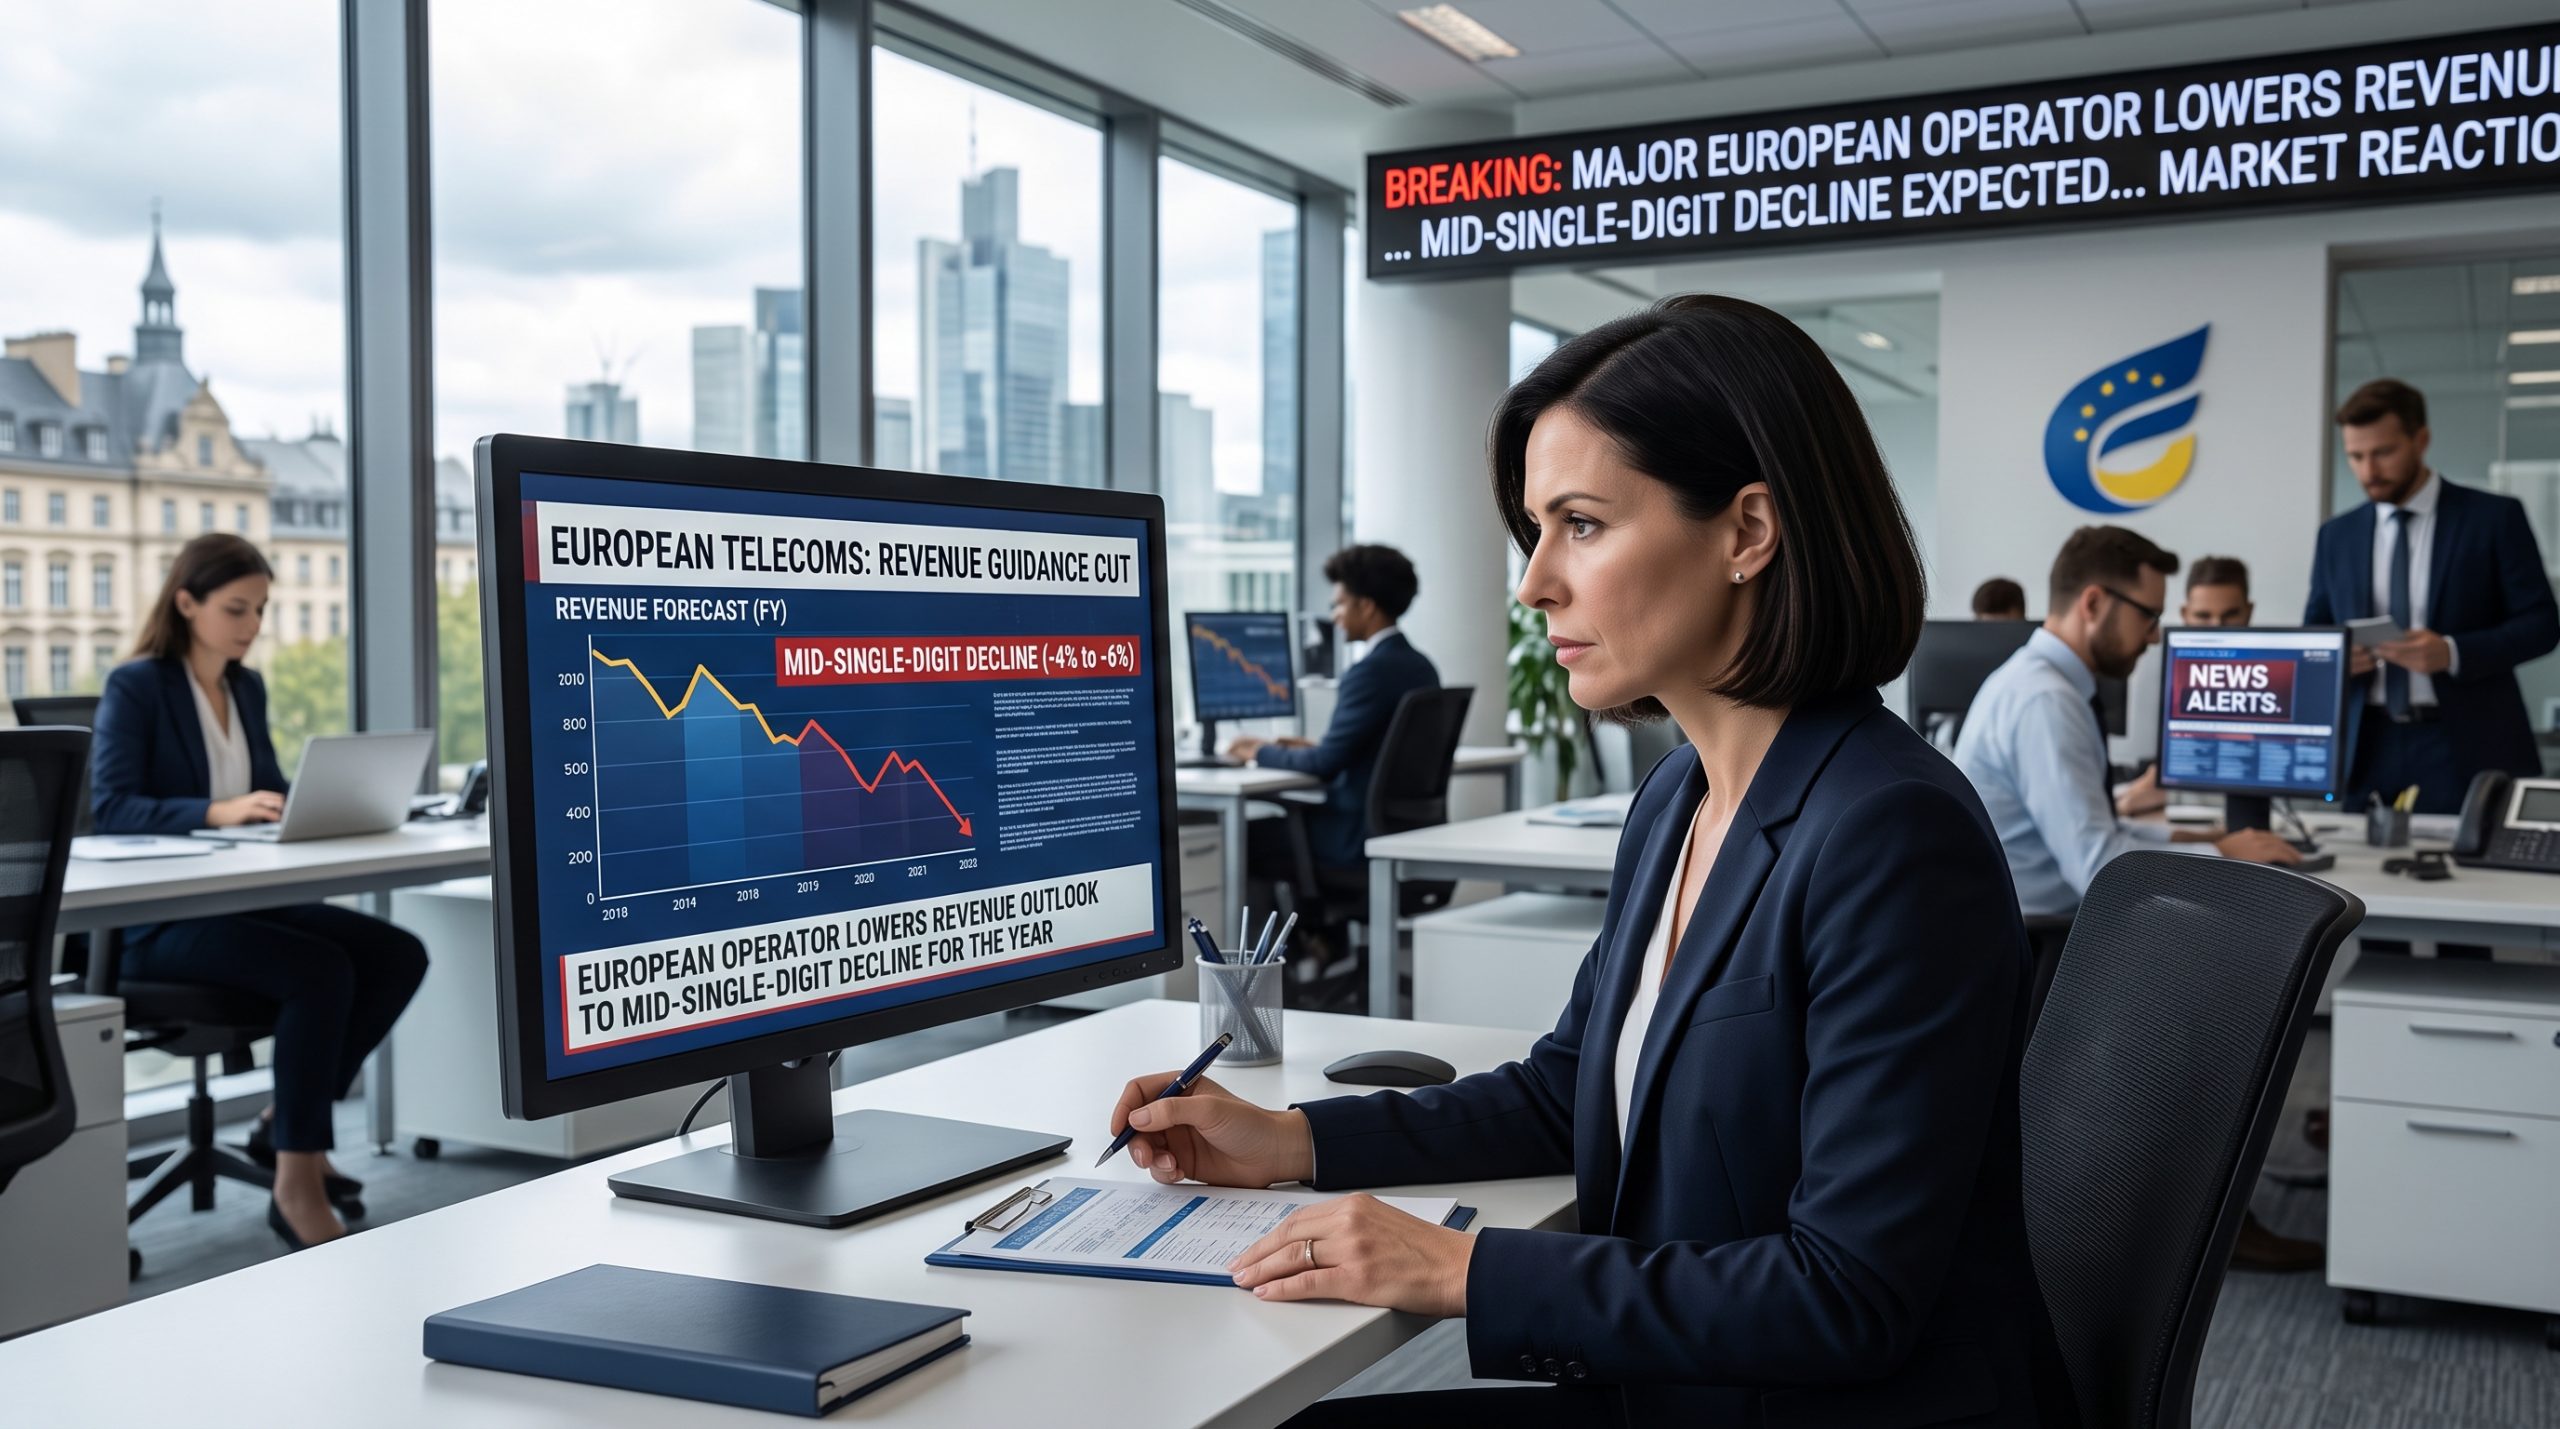
A European operator group has cut its full-year revenue outlook, now forecasting a “mid-single digit” decline rather than the “low-single digit” drop it had previously guided toward. The revision signals sharper pressure on the group’s top line than management had earlier anticipated, and it lands at a moment when investors are scrutinising every downward adjustment across the sector. For shareholders, lenders, and competitors watching the group’s trajectory, the direction of travel matters more than the exact figure.
What the Guidance Cut Signals for Investors
The shift from one revenue band to another reads as a small semantic step. In practice, it is not. Moving from “low” to “mid” single-digit territory roughly doubles the expected rate of decline, and that kind of recalibration rarely happens in isolation.
- Steeper contraction than modelled: The revised band implies the group now expects revenue to fall at close to twice the pace it signalled under its earlier outlook.
- Analysts will likely revisit full-year earnings models, since revenue assumptions feed directly into margin and cash-flow projections.
- Confidence signal: A mid-year guidance cut can erode market trust in management’s forecasting, even when the underlying business remains stable.
- Lenders and ratings reviewers tend to treat downward revisions as a prompt to re-examine covenant headroom.
Reading the Revision in Context
Guidance exists to set expectations. When an operator narrows or shifts its range, it is telling the market something about demand, pricing, or cost that the previous number no longer captured. The group has framed the change as a revenue story rather than a structural one, though the distinction is not always as clean as it sounds on an earnings call (a point sceptical analysts rarely let slide).
What remains less clear is whether the pressure is concentrated in a single business line or spread across the portfolio. That difference shapes how durable the decline turns out to be. A one-off hit to a specific revenue stream is one thing; a broad-based softening is another entirely.
Operators across Europe have spent recent reporting cycles navigating margin compression, shifting consumer demand, and currency effects that distort reported figures. Against that backdrop, a revised outlook from one group feeds a wider narrative about where the sector’s growth is actually coming from. Investors tracking peers such as major European telecommunications operators and their quarterly guidance will read this cut as one more data point in a crowded picture.
The Business Impact Beyond the Headline Number
A revenue decline does not automatically translate into a proportional earnings hit. Cost discipline, pricing adjustments, and operational efficiency can cushion the bottom line even when the top line slips. But the cushion only stretches so far.
| Metric | Previous Guidance | Revised Guidance |
|---|---|---|
| Expected revenue trend | Low-single-digit decline | Mid-single-digit decline |
| Implied pace of contraction | Modest | Roughly double the prior rate, with knock-on effects for margin modelling |
| Market read | Manageable softness | Sharper pressure than forecast |
The practical question for management is how much of the gap can be absorbed through cost levers and how much flows straight to profit. That calculation will dominate the next set of results.
Why the Timing Carries Weight
Guidance revisions issued mid-cycle tend to attract more attention than those bundled into scheduled annual updates. They suggest conditions moved faster than the group’s internal forecasting allowed for. And while a single adjustment does not define a trajectory, it does hand competitors and analysts a reference point they will measure the next quarter against.
The precedent is simple. Having moved its range once, the group has set a bar: the market will now watch closely to see whether the mid-single-digit figure holds, or whether it too gets revised. Either outcome tells a story.
Key Questions Executives Are Asking
Does a mid-single-digit revenue decline threaten profitability?
Not necessarily. Revenue and earnings move together, but cost management and pricing can soften the impact on margins. The risk lies in how much of the decline the group can offset before it reaches the operating line.
Why does moving from “low” to “mid” single digits matter so much?
Because it roughly doubles the expected rate of decline. In forecasting terms, that is a material recalibration, not a rounding adjustment.
What should investors watch next?
The next earnings release, and specifically whether the revised band holds. A second cut would raise harder questions about forecasting discipline than the first.
Is this a sector-wide trend or company-specific?
The group has framed it as its own revenue issue. Still, several European operators have reported pressure on growth, so it is worth reading alongside peer results rather than in isolation.
What Comes After the Revision
The group’s immediate task is credibility. One guidance cut is explained; a pattern is scrutinised. Management will need to demonstrate that the mid-single-digit figure reflects a floor, not a staging post on the way down.
For the wider market, the revision adds to an accumulating body of evidence about where European operators stand on growth. Regulators, lenders, and rival operators now have a fresh benchmark against which to judge the group’s next move. And the number that matters most is the one that has not been reported yet.